Showing posts with label home builder. Show all posts

Monday, April 18, 2011

Homebuilder Blues: NAHB/Wells Fargo Home Builder Ratings April 2011

Today, the National Association of Home Builders (NAHB) released their latest Housing Market Index (HMI) showing a slight decline for most measures with the "buyer traffic" index remaining near record lows as home builders continue to plod through the weakest activity seen in generations.

It's important to recognize that currently all measures are showing either notable year-over-year declines or, for the buyer traffic index, zero change in the level of activity seen since last year.

Clearly the new home market has seen another no-show start to the buying season with the typically strongest selling months (remember Bob Toll's analysis of the seasons) fully behind it.

The new home market will likely not resume any significant form of healthy function until the considerable overhang of inventory is cleared.


Monday, March 15, 2010

Homebuilder Blues: NAHB/Wells Fargo Home Builder Ratings March 2010

Today, the National Association of Home Builders (NAHB) released their latest Housing Market Index (HMI) showing declining results for all measures.

It's important to recognize that although each sentiment index has now shown notable year-over-year increases, their levels still remain near the worst levels seen in over 20 years.

The new home market will likely not resume any significant form of healthy function until the considerable overhang of inventory is cleared.


Monday, June 15, 2009

Homebuilder Blues: NAHB/Wells Fargo Home Builder Ratings June 2009

Today, the National Association of Home Builders (NAHB) released their latest Housing Market Index (HMI) showing a decline to the overall index as well as at best a flattening to most component indices.

It’s important to recognize that although the series are seasonally adjusted, each series has generally shown notable strength or noticeable flattening during the first quarter of each of the last 4 years.

Now that the early season optimism has likely run its course, look for these indices to turn southward again as builders more clearly contemplate the horrendous condition of their market.

The new home market will likely not resume any significant form of healthy function until the considerable overhang of inventory is cleared and with unemployment on the rise and the level of completion still unusually high, it appears that the overhang is here to stay.

Each component of the NAHB housing market index remains WELL BELOW the worst levels ever seen in the over 20 years and continues to remain firmly in uncharted territory.


Friday, April 24, 2009

New Home Sales: March 2009

Subtitle: No Bottom…

Today, the U.S. Census Department released its monthly New Residential Home Sales Report for March showing continued deterioration in demand for new residential homes across virtually every tracked region resulting in a 30.6% year-over-year decline and a truly horrendous 74.37% peak sales decline nationally.

The following charts show the extent of sales declines seen since 2005 as well as illustrating how the further declines in 2009 are coming on top of the 2006, 2007 and 2008 results (click for larger versions)


It’s important to note that although the new home sales data appears to have prompted the traditional media to make many “bottom calls” recently, the evidence for their conclusions are scant.

First, most “bottom callers” have focused too closely on just the new home sales series and its historic bottoms rather than other important indicators that disclose a more complete state of the new home market.

As I have argued recently, the level of inventory and supply and level of completed new homes are still too high for a real sustained bottom for the new home market.

The following chart (click for larger) plots the new home sales (SAAR) series along with the current inventory level (NA) and the level of homes completed (NA) since 1973.

As you can see, although the new home sales series has breached the lowest level in over 30 years, the level of inventory (homes for sale at end of period) still remains higher than past historic bottoms and the level of homes completed remains much higher.

Make no mistake, I’m not suggesting that these three series will all bottom simultaneously, a simple cursory review of the chart above will dispel that notion, BUT I believe that if you consider the downward trend in home prices, the state of the job market, the lack of credit availability as well as the extent of the former boom (just look at the run builders had above.. steadily increasing sales from January 1991 to July 2005… truly unparalleled!) any sustained bottom is still a long way off.

The new home market might be in the process of clearing but at the moment it still looks seriously impaired and of the steadily shrinking pool of prospective buyers (from lack of confidence, lack of job or lack of cash and credit availability) those who wait to buy will almost certainly continue to find better pricing…. Thus sales will continue to fall.

Look at the following summary of today’s report:

National

  • The median sales price for a new home declined 12.17% as compared to March 2008.
  • New home sales were down 30.6% as compared to March 2008.
  • The inventory of new homes for sale declined 33.7% as compared to March 2008.
  • The number of months’ supply of the new homes has decreased 4.5% as compared to March 2008 and now stands at 10.7 months.
Regional

  • In the Northeast, new home sales were down 32.1% as compared to March 2008.
  • In the Midwest, new home sales were down 32.9% as compared to March 2008.
  • In the South, new home sales were down 29.7% as compared to March 2008.
  • In the West, new home sales were down 31.1% as compared to March 2008.

Wednesday, February 18, 2009

Homebuilder Blues: NAHB/Wells Fargo Home Builder Ratings February 2009

Yesterday, the National Association of Home Builders (NAHB) released their latest Housing Market Index (HMI) showing dramatic new lows and continued evidence that the new home market is experiencing a prolonged bout of depression.

Each component of the NAHB housing market index remain WELL BELOW the worst levels ever seen in the over 20 years the data has been being compiled strongly suggesting that the current severe contraction has surpassed all other events seen in the last 22 years and is now firmly in uncharted territory.


Monday, August 18, 2008

Homebuilder Blues: NAHB/Wells Fargo Home Builder Ratings August 2008

Today, the National Association of Home Builders (NAHB) released their latest Housing Market Index (HMI) showing continued evidence that the new home market is experiencing a prolonged bout of depression.

The release came along with some hopeful “bottom searching” outlook from Chief Economist David Seiders.

“While our overall measure of builder confidence remains at a record low at this time, it is a good sign that two out of three of the HMI’s component indexes rose in August, and this may be an indication that we are nearing the bottom of the long downswing in new-home sales, … Our current forecast shows stabilization of sales during the second half of this year, followed by solid recovery in 2009 and beyond.”

Each component of the NAHB housing market index is now sitting WELL BELOW the worst levels ever seen in the over 20 years the data has been being compiled strongly suggesting that the current severe contraction has surpassed all other events seen in the last 22 years and is now firmly in uncharted territory.


Wednesday, January 16, 2008

Homebuilder Blues: NAHB/Wells Fargo Home Builder Ratings January 2008

Today, the National Association of Home Builders (NAHB) released their Housing Market Index (HMI) showing continued evidence that the new home market is experiencing a prolonged recession.

The release came along with some guarded, yet optimistic, outlook from Chief Economist David Seiders who has continues to look for an “upswing” in building activity in the second half of 2008.

“The HMI has held within a narrow two-point range for the past five months, indicating that builder views of housing market conditions essentially haven’t changed over that time, … Builders are anticipating a time when market conditions will support an upswing in building activity – most likely in the second half of 2008.”

With this month’s release the NAHB has apparently discontinued (I’m looking into it… I’ll post what I find out) publishing the individual builder respondent rating (“good”, “fair” and “poor”) data series that are the components of the overall composite HMI series, so I have reworked my charts to simply show the four main composites; the HMI index, the “present conditions” index, the “future conditions” index and the “buyer traffic” index.

It’s important to understand that each component of the NAHB housing market index is now sitting at or near the worst levels ever seen in the over 20 years the data has been being compiled.

This suggests that the current severe contraction has surpassed all other events seen in the last 22 years and is now firmly in uncharted territory.


Friday, November 30, 2007

Constructing Capitulation: October 2007

Looking back at October’s results (released throughout November) it’s now unequivocally obvious that the nation’s housing markets, having fully transcended the mania that existed primarily in the first half of the decade and now, in its aftermath, after being dramatically and irreparably impaired by the unwinding of the resultant mortgage-credit debacle, are now hurtling headlong into a dramatic new leg down.

While housing demand continues to slow and inventories swell far beyond historic levels, the credit markets that had provided such a plentiful supply of cheap Jumbo mortgages remains non-existent.

Homebuilders have now clearly accepted the severity of the recession and are re-pricing accordingly but, as is typical, the existing home sellers remain behind the curve.

Additionally, there are tentative signs that the commercial real estate market (CRE) is now beginning to feel the effects of the ongoing credit debacle and consumption pullback resulting in a sharp pullback in prices and swelling inventory of vacant space.

Finally, although the second preliminary installment of the Q3 2007 GDP showed strong results, most notably coming from exports, the mainstay consumer and CEO confidence surveys are now clearly showing significant trepidation particularly with respect to future prospects for the strength of the economy.

The Pending Home Sales Report, the most leading existing home sales indicator, again showing truly stark and horrendous continuation of the historic decline to residential housing on a year-over-year basis, both nationally and in every region.

We are now firmly heading down the second slope of the pullback in residential housing demand with the Northeast, Midwest, West and the National regions having now fallen over 30% BELOW the seasonally adjusted home sales activity recorded in 2001, the first year Pending Home Sales were tracked.


The National Association of Realtors (NAR) released their ninth consecutive downward revision to their annual home sales forecast for 2007 putting the current outlook far below the “rose colored” initial predictions from the start of the year.

NAR’s Existing Home Sales Report showing perfectly clearly, that demand for residential real estate, for both single family and condos, has now taken a new and substantial leg down uniformly across the nation’s housing markets likely as a direct result of the momentous and ongoing structural changes in the credit-mortgage markets.

Furthermore, the latest quarterly results for existing home sales shows that, on a year-over-year basis, home sales are now falling in every state except for Vermont and North Dakota (see chart below and click for larger version and note that NH and Idaho don’t report sales data) and even those states sales growth are anemic.


Homebuilder confidence is now sitting AT OR BELOW the worst levels ever seen in the over 20 years the data has been being compiled.

This suggests that the current severe correction has surpassed all other events seen in the last 22 years and is now firmly in uncharted territory.

The Census Department’s New Residential Construction Report firmly indicates a new leg down in the decline for residential construction showing substantial declines on a year-over-year and month-to-month basis to single family permits both nationally and across every region.

The Census Department’s New Residential Home Sales Report for October that again confirmed the hideous falloff in demand for new residential homes both nationally and in every region as well as reporting significant downward revisions to July, August and September’s results.

As with prior months, home sales and median prices are still declining significantly, with the national measure of sales dropping a truly ugly 23.5% and the median selling price declining a whopping 13.02% as compared to October 2006.

The September 2007 results of the S&P/Case-Shiller home price indices continued to show significant weakness for the nation’s housing markets with 13 of the 20 metro areas tracked reporting year-over-year declines and now ALL metro areas showing declines from their respective peaks.

Topping the list of peak decliners are Detroit at -12.77%, Tampa at -11.74%, Miami at -11.13%, San Diego at -10.99%, Phoenix at -9.74%, Las Vegas at -9.08% and Washington DC at -8.92%.


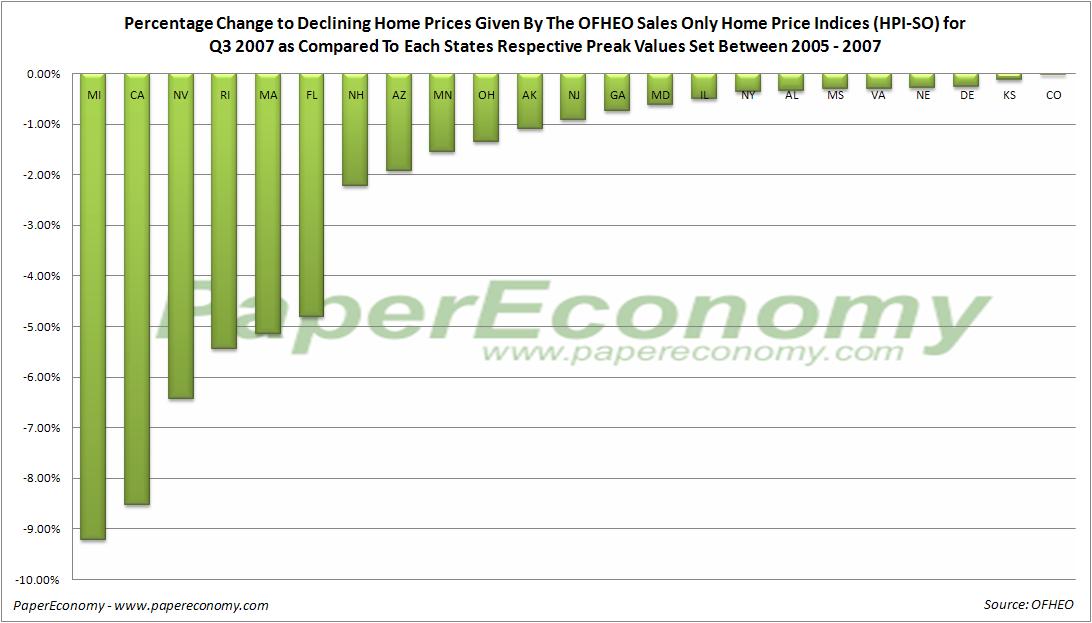
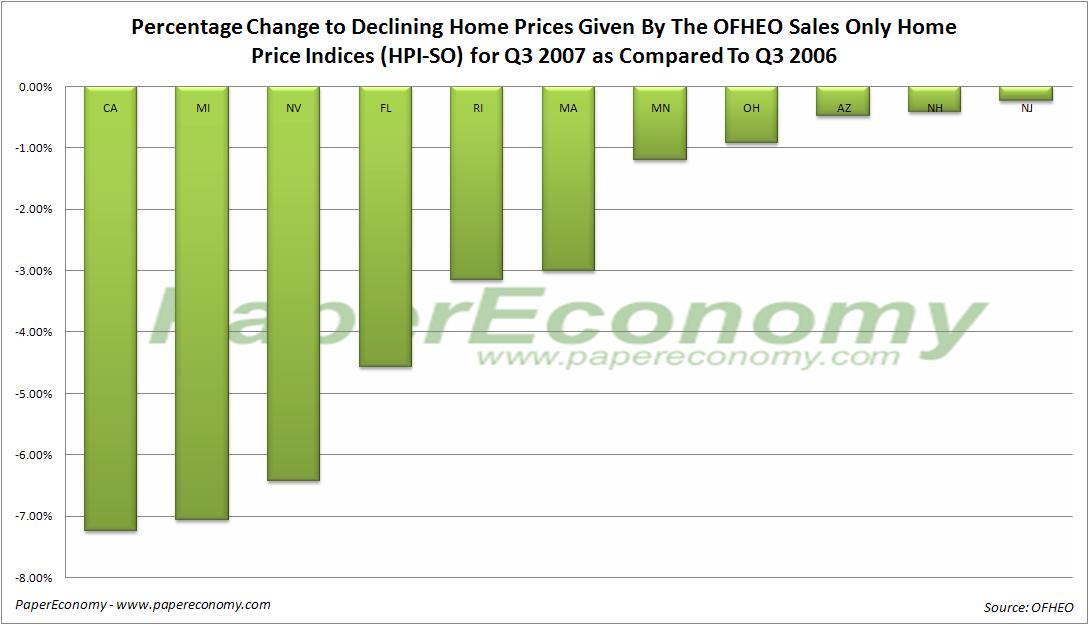
The Office of Federal Housing Enterprise Oversight (OFHEO) released their Q3 2007 home price indices showing continued deceleration of home price appreciation in most regions as well as a broadening of outright declines now including 23 states declining from their respective peaks and 11 states declining on a year-over-year basis.

Topping the list of peak decliners by state is Michigan at -9.22%, California at -8.52%, Nevada at -6.43%, Rhode Island at -5.45%, Massachusetts at -5.14%, Florida at -4.81% and New Hampshire at -2.22%.

Topping the list of year-over-year decliners by state is California at -7.24%, Michigan at -7.07%, Nevada at -6.43%, Florida at -4.56%, Rhode Island at -3.16% and Massachusetts at -3.01%.


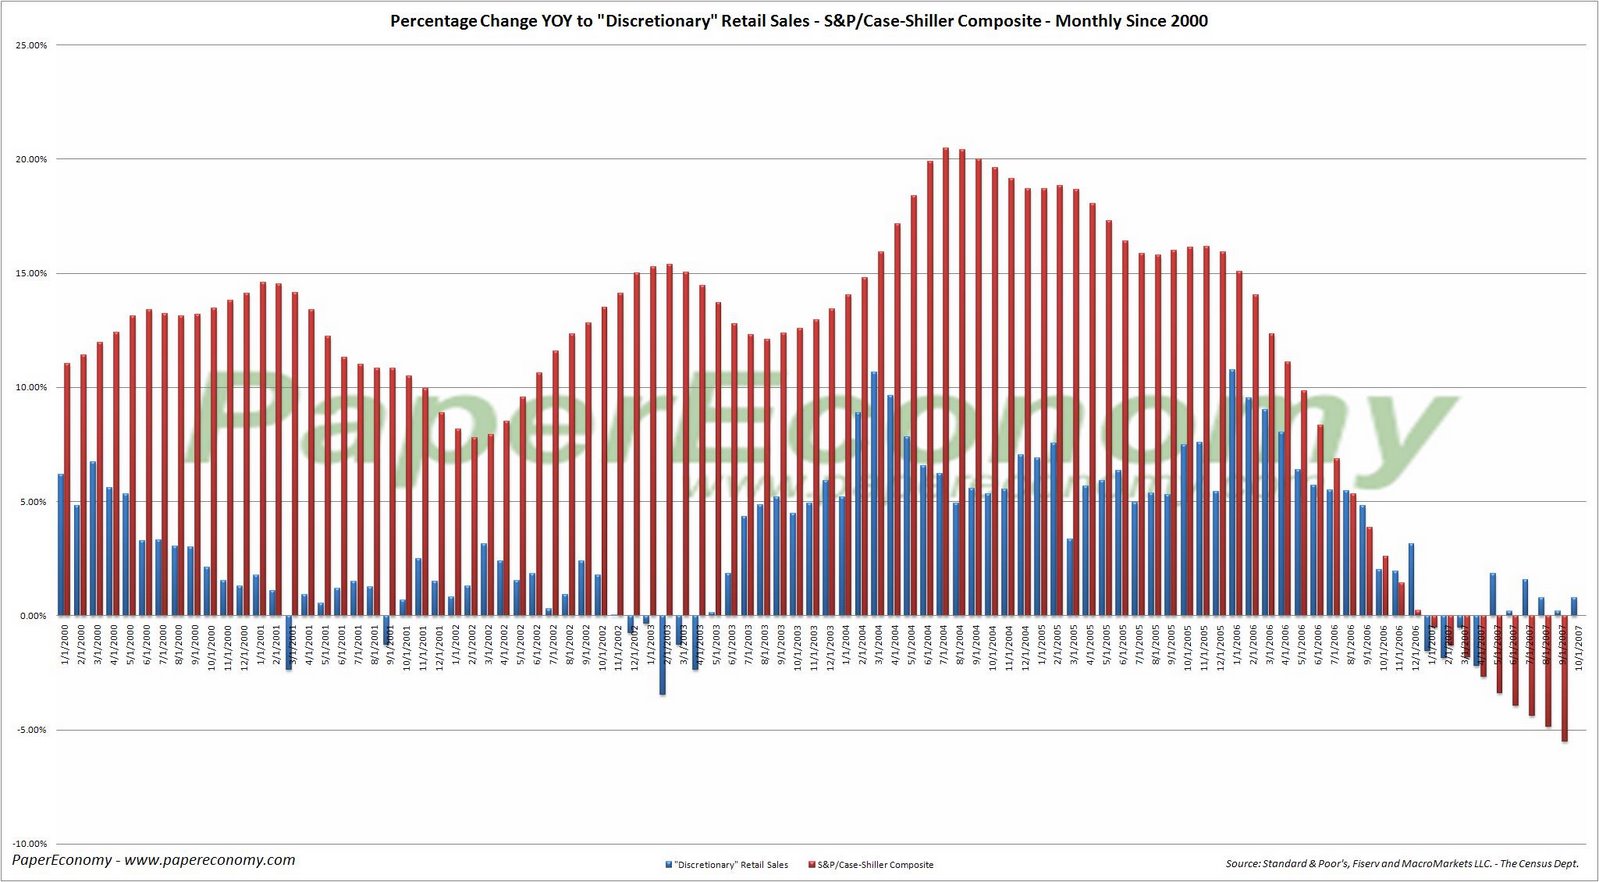
The housing weakness still appears to be contributing to a pullback in the retail sales of the most discretionary goods although I will continue to revise the procedures for determining this correlation later this month.

Countrywide Financial (NYSE:CFC) continues to register tremendous borrower stress as delinquencies and foreclosures are continuing to remain at troubling levels with delinquencies climbing 32.96% and foreclosures continuing to soar over 112% since October of 2006.

The latest release of the Reuters/University of Michigan Survey of Consumers showed in unequivocal terms that the US consumer is feeling the burn from declining home values, increased fuel costs and a general uncertainty about the future of the economy.

The Index of Consumer Sentiment fell 17.37% as compared to November 2006 mostly as a result of consumers’ expectations of future economic prospects.

The Index of Consumer Expectations (a component of the Index of Leading Economic Indicators) fell a whopping 20.43% below the result seen in November 2006.

As for the current circumstances, the Current Economic Conditions Index fell 13.68% as compared to the result seen in November 2006.

The Federal Reserve released their monthly read of industrial production showing a decrease of 0.5% from September and a 1.8% increase since October 2006.

More importantly though, production of “final product” consumer durable goods have been showing some recent weakness, with particularly significant declines coming specifically from home appliances, furniture and carpeting.

There has been growing speculation that the commercial real estate (CRE) markets will inevitably follow the lead of the residential markets down to a recessionary correction.

After having some substantial growth between 2003 and Q2 2007 (particularly during 2005 – 2006), there has been a precipitous 2.5% drop in Q3 2007, a drop that MIT/CRE Director David Geltner sees as non-trivial.

"The fall in our index is the first solid, quantitative evidence that the subprime mortgage debacle, which hit the broader capital markets in August, may be spreading to the commercial property markets."


The preliminary GDP report for Q3 2007 showed an increase in the severity of the drag coming from the decline in residential fixed investment, that is, all investment made to construct or improve new and existing residential structures including multi–family units, with the current quarterly fall-off registering a whopping decline of 19.7% since last quarter while shaving 1.03% from overall GDP.

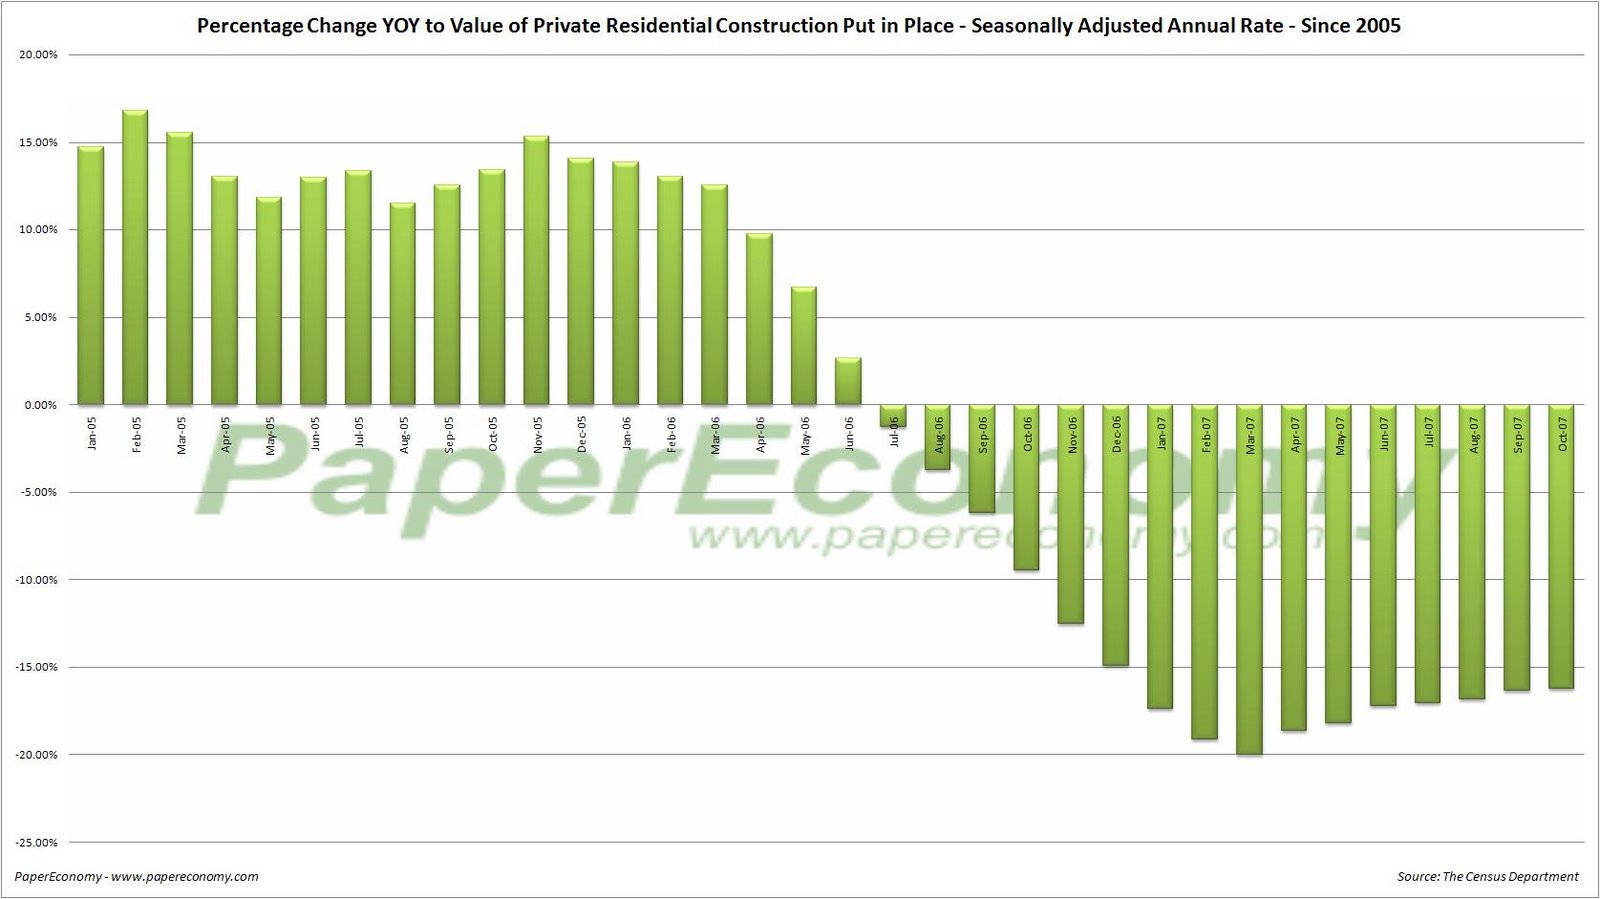
Finally, the Census Department’s Construction Spending report for September again demonstrated the significant extent to which private residential construction spending is contracting.

With the weakening trend continuing, total residential construction spending fell -16.23% as compared to October 2006 and 27.63% from the peak set in February 2006 while private single family construction spending declined by a grotesque -26.41%.